
Meta description: Learn how to remove collections from your credit report legally in 2026. Dispute errors, negotiate pay-for-delete, and boost your score fast.
Introduction: The $5,000 Mistake That Haunts Your Credit
Mark never checked his credit report. Not once in five years.
Then he applied for a car loan in March 2026. The dealer ran his credit, frowned, and showed him the screen: four collections totaling $3,800—medical bills he didn’t even know existed.
His interest rate? 18.9% APR instead of the 5.9% advertised.
That one oversight cost him $5,200 extra over the life of the loan.
Collections are credit score killers. A single collection can drop your score 50-100 points. Multiple collections? You’re looking at 100-200 points gone, pushing you from «fair» credit to «poor» territory.
But here’s what collection agencies don’t want you to know: many collections are removable. Errors, outdated debts, unverifiable accounts—legally, these must come off your report.
In this guide, I’ll show you the exact step-by-step process to remove collections from your credit report in 2026. No scams, no illegal tricks—just proven strategies that work.
What Are Collections and Why Do They Hurt So Much?
When you fail to pay a debt (credit card, medical bill, utility, etc.), the original creditor eventually sells or assigns it to a collection agency.
| Stage | Timeline | Impact |
|---|---|---|
| Missed payment | 30 days late | Minor score drop (-20 to -40) |
| Charged off | 180 days late | Major drop (-50 to -100) |
| Sent to collections | 6+ months | Severe damage (-100 to -150) |
| Multiple collections | Ongoing | Catastrophic (below 500 possible) |
Why collections hurt more than late payments:
- They signal default, not just delay
- They stay on your report for 7 years from first delinquency
- They make lenders extremely hesitant to approve you
Step 1: Get Your Full Credit Reports (Free)
Before fighting anything, know exactly what you’re facing.
| Source | Cost | Details |
|---|---|---|
| AnnualCreditReport.com | Free | Official site, all 3 bureaus weekly |
| Credit Karma | Free | TransUnion & Equifax, updated weekly |
| Experian.com | Free | Experian report, FICO score |
What to look for:
- Name of collection agency
- Original creditor
- Amount owed
- Date opened
- Date of first delinquency
Critical: Note the «Date of First Delinquency»—this determines when the 7-year clock expires. Collection agencies sometimes «re-age» debts illegally.
Step 2: Verify the Debt Is Legitimate
Never pay a collection without verifying it first. Errors are shockingly common:
| Error Type | How Common | What To Do |
|---|---|---|
| Not your debt | ~10% of collections | Dispute immediately |
| Wrong amount | ~15% | Request debt validation |
| Already paid | ~5% | Provide proof of payment |
| Too old (7+ years) | ~8% | Dispute as obsolete |
| No documentation | ~20% | Challenge validity |
Your right under the Fair Debt Collection Practices Act (FDCPA): You can demand the collector prove you owe the debt.
Step 3: Send a Debt Validation Letter
This is your most powerful tool. If the collector can’t prove the debt, they must remove it.
Sample Debt Validation Letter
[Your Name]
[Your Address]
[City, State ZIP]

[Date]

[Collection Agency Name]
[Collection Agency Address]

Re: Account Number [XXXX-XXXX-XXXX]
Original Creditor: [Creditor Name]
Amount Alleged: $[Amount]

Dear [Collection Agency],

I am writing to request validation of the debt referenced above. Under the Fair Debt Collection Practices Act (FDCPA), 15 U.S.C. § 1692g, I have the right to request complete verification of this debt.

Please provide the following:
1. The original signed contract or agreement
2. Complete payment history from the original creditor
3. Proof that you are licensed to collect debt in [your state]
4. Calculation showing how the current balance was determined
5. Documentation proving this debt is within the statute of limitations

If you cannot provide complete validation, I request that you:
- Cease all collection activities
- Remove this account from my credit reports with Equifax, Experian, and TransUnion
- Confirm in writing that this matter is closed

I request a response within 30 days of receipt of this letter.

Sincerely,
[Your Signature]
[Your Printed Name]
Send via certified mail with return receipt requested. Keep copies of everything.
Step 4: Dispute Errors With Credit Bureaus
If the debt is wrong, outdated, or unverifiable, dispute directly:
Online Dispute (Fastest)
| Bureau | Website | Timeline |
|---|---|---|
| Equifax | equifax.com/personal/credit-report-services/credit-dispute | 30 days |
| Experian | experian.com/disputes/main.html | 30 days |
| TransUnion | transunion.com/credit-disputes/dispute-your-credit | 30 days |
What happens:
- Bureau investigates with collector
- If collector can’t verify → deleted from report
- If verified → stays, but you can escalate
What to include in your dispute:
| Document | Purpose |
|---|---|
| Copy of credit report showing error | Identifies specific item |
| Debt validation letter (if sent) | Shows you challenged validity |
| Proof of payment (if applicable) | Proves debt is satisfied |
| Identity theft report (if applicable) | Shows fraud |
Step 5: Negotiate «Pay for Delete»
If the debt is legitimate and verified, your best option is negotiating removal.
«Pay for delete» means: You pay the debt (or a settlement), and the collector removes the collection from your credit report.
Negotiation Script (Phone)
«I acknowledge this debt. I’m willing to resolve it, but I need the collection removed from my credit report as a condition of payment. Can you send me a ‘pay for delete’ agreement in writing?»
Key negotiation tactics:
| Tactic | How It Works |
|---|---|
| Offer 30-50% of balance | Collectors often buy debts for pennies on the dollar |
| Get everything in writing | Verbal promises mean nothing |
| Don’t pay until you have the agreement | Signed letter before any money changes hands |
| Pay with cashier’s check or money order | Creates paper trail, avoids giving bank account access |
Sample Pay-for-Delete Agreement
PAY FOR DELETE AGREEMENT

Date: [Date]

Collection Agency: [Name]
Account Number: [XXXX-XXXX-XXXX]
Original Creditor: [Name]
Balance: $[Amount]

Agreement: [Collection Agency] agrees to accept $[Settlement Amount]
as full satisfaction of the above debt. Upon receipt of payment,
[Collection Agency] will remove this account from the credit reports
of Equifax, Experian, and TransUnion within 30 days.

This agreement is binding upon signature.

_________________________
[Collection Agency Representative]

_________________________
[Your Name]
Step 6: Handle Medical Collections (Special Rules)
Medical collections have unique protections as of 2023-2026:
| Rule | What It Means |
|---|---|
| Paid medical collections removed | If you pay, it comes off (as of 2023) |
| Unpaid under $500 ignored | Medical debts under $500 don’t count |
| 180-day grace period | Collectors must wait before reporting |
| Insurance disputes protected | Debts under insurance review can’t be reported |
Strategy for medical collections:
- Check if debt is under $500 → If yes, dispute as «exempt»
- If over $500, check if insurance should have paid
- If insurance error, dispute with collector and insurance
- If you must pay, pay in full → automatic removal
Step 7: Escalate If Necessary
If collectors refuse to cooperate, you have options:
| Action | When to Use | Result |
|---|---|---|
| CFPB Complaint | Collector violates FDCPA | Federal investigation |
| State Attorney General | State law violations | State enforcement |
| Consumer Protection Lawyer | Complex cases, large debts | Potential lawsuit/settlement |
| Credit Repair Company | Overwhelmed, multiple collections | They handle disputes (fees apply) |
Warning: Avoid credit repair companies promising instant results or charging upfront. Legitimate companies charge only after work is performed.
Timeline: What to Expect
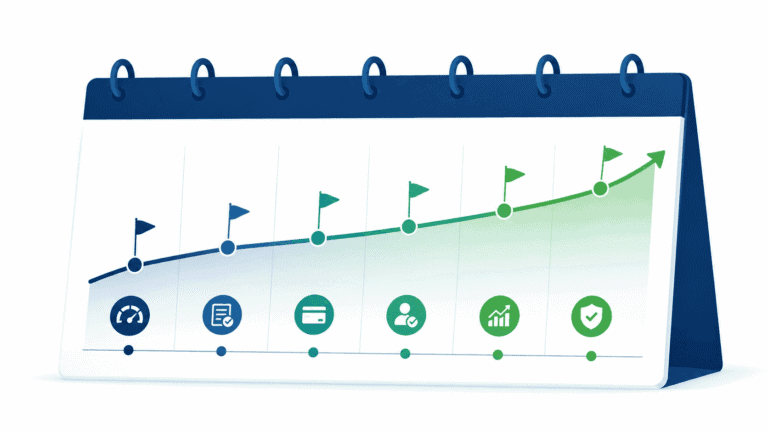
| Week | Action | Expected Result |
|---|---|---|
| 1 | Pull reports, identify collections | Complete inventory of debts |
| 2 | Send debt validation letters | Collectors must respond in 30 days |
| 3-4 | Dispute errors with bureaus | Bureaus investigating |
| 5-6 | Receive validation responses or lack thereof | Some debts may be unverifiable |
| 7-8 | Negotiate pay-for-delete on valid debts | Signed agreements |
| 9-10 | Make payments per agreements | Collections marked paid |
| 11-12 | Verify removals on updated reports | Score improvement visible |
Typical score improvement:
- 1 collection removed: +50 to +75 points
- 2-3 collections removed: +100 to +150 points
- All collections removed: +150 to +200+ points
Common Mistakes That Backfire
| Mistake | Why It Hurts | What To Do Instead |
|---|---|---|
| Paying without «pay for delete» | Collection stays, just marked «paid» | Always negotiate removal first |
| Ignoring the debt | Worsens credit, risk of lawsuit | Actively dispute or negotiate |
| Making partial payments | Resets statute of limitations | Negotiate lump sum settlement |
| Admitting debt on phone | Can be used against you | Keep communications in writing |
| Disputing online only | Less documentation | Also send certified mail |
FAQ: Removing Collections
How long do collections stay on my credit report?
7 years from the date of first delinquency with the original creditor. Paying doesn’t reset this clock.
Will paying a collection improve my score?
Not automatically. A paid collection still hurts your score. Only removal (via pay-for-delete or dispute) helps significantly.
Can I remove collections myself, or do I need a company?
You can absolutely do it yourself. The process is straightforward. Companies charge $50-$150/month for work you can do free.
What if the collector won’t do «pay for delete»?
Options:
- Offer higher settlement (60-70%)
- Wait until debt is near 7-year expiration
- Focus on building positive credit to offset the negative
Can collections lead to wage garnishment?
Yes, but only after a lawsuit and court judgment. Most collectors prefer settlement over costly litigation.
Do collections affect my ability to rent an apartment?
Yes. Most landlords check credit and reject applicants with unpaid collections. Removing them significantly improves approval odds.
Conclusion: Take Control of Your Credit Today
Collections don’t have to define your financial future. Whether through dispute, validation, or negotiation, you have powerful tools to remove them.
Remember:
- Verify first — never assume a collection is legitimate
- Document everything — certified mail, written agreements
- Negotiate removal — «paid» status helps less than deletion
- Stay persistent — collectors count on you giving up
Your action plan for TODAY:
- ✅ Pull free credit reports from all 3 bureaus
- ✅ List every collection with amount, date, and collector
- ✅ Identify any errors or questionable debts
- ✅ Send debt validation letters for unverified debts
- ✅ Begin dispute process for confirmed errors
Six months from now, your credit report could look completely different.
Related guides:
- How to Dispute Credit Report Errors in 2026
- How to Build Credit From 500 to 700 in 2026
- How Long Does It Take to Rebuild Credit in 2026?
Disclaimer: This content is for educational purposes only and does not constitute legal or financial advice. The Fair Debt Collection Practices Act (FDCPA) provides specific rights; consult a consumer protection attorney for complex situations. Individual results vary.
2 comentarios