How Long Should You Wait Before Applying for New Credit After Starting From Zero?
Written by Credit Builder Guide Editorial Team
Credit Builder Guide is dedicated to helping Americans understand credit scores, improve financial habits, rebuild damaged credit, and make smarter borrowing decisions through simple, research-based educational content.
Fact-checked using trusted U.S. financial resources • Updated for 2026
Getting approved for that first credit card or credit-builder loan feels like a milestone — and it often leads to an obvious next question: how soon can another account be added to speed things up? The instinct to add more credit quickly is understandable, but timing matters more than most first-time credit users realize.
This guide covers how to think about timing a second credit account after starting from zero, without slowing down progress or taking on unnecessary risk.
The Temptation to Apply for More Credit Too Soon
After a first approval, it’s common to feel motivated to add a second or third account right away, whether to increase available credit, diversify credit mix, or simply take advantage of a new offer. But a brand-new credit file is fragile, and applying too aggressively can work against the very progress a first-time credit user is trying to build.
What Actually Happens When You Apply for New Credit
Each new credit application typically results in a hard inquiry on the credit report, which can cause a small, temporary dip in the score. A new account, once opened, also lowers the average age of accounts on the file — a factor that matters more the fewer accounts someone has. On a file with just one existing account, adding a second immediately can have a proportionally larger effect on average account age than it would on a file with ten existing accounts.
Do You Need a Score Before You Can Apply Again?
Most scoring models require a minimum amount of reported history — often a few months of activity on at least one account — before a score can be generated at all. Applying for a second account before a score even exists means the new lender is evaluating the application with very limited data, which can affect both approval odds and the terms offered.
A General Guideline for Timing Your Second Account
While there’s no single rule that applies to everyone, many first-time credit users find it reasonable to wait at least six months to a year after opening a first account before applying for a second one. This generally allows enough time for a score to be generated and for a consistent payment pattern to be established, which can improve approval odds and terms on the next application compared to applying too early with a still-unproven file.
Signs You’re Ready for a Second Account
- You’ve made several consecutive on-time payments on your first account.
- A credit score has been generated and is visible through your card issuer or a free monitoring tool.
- Your utilization on the first account has stayed consistently low.
- You have a specific, genuine reason for the second account, such as needing installment credit or a card better suited to your current spending.
Signs You Should Wait Longer
- Your first account is less than a few months old and hasn’t generated a score yet.
- You’ve had a late payment or high utilization recently that you’re still working to offset with positive history.
- You’re applying mainly out of impatience or to chase a promotional offer, rather than a genuine need.
- You already have an upcoming major application planned, such as a car loan or apartment lease, where a fresh hard inquiry could work against you.
How Hard Inquiries Factor Into the Decision
A single hard inquiry typically has a small, temporary effect on a score, but several inquiries within a short period can compound that effect, especially on a thin file with little other data to balance it out. This is part of why spacing out applications — rather than applying for several accounts back-to-back — tends to be the more conservative and often more successful approach for someone still establishing their credit file.
Common Mistakes When Timing New Applications
- Applying for a second account within days or weeks of the first, before any payment history has even had a chance to be reported.
- Applying for multiple cards at once «just to see» which one approves, generating several hard inquiries unnecessarily.
- Ignoring an existing late payment and applying for new credit anyway, rather than waiting for the file to stabilize first.
- Waiting far too long out of excessive caution, when the underlying file is actually ready to responsibly support a second account.
FAQ: Timing New Credit Applications
Is there an official rule for how long to wait between credit applications?
No single official rule applies to everyone. General guidance suggests waiting until a first account has generated a score and shown a consistent payment pattern, often around six months to a year, though individual circumstances vary.
Will applying for a second card right away ruin my credit?
It’s unlikely to cause lasting damage on its own, but it can lead to a lower approval odds or a small, temporary score dip, and it may not reflect the strongest possible application compared to waiting for more history to build.
Does it matter what type of account I add second?
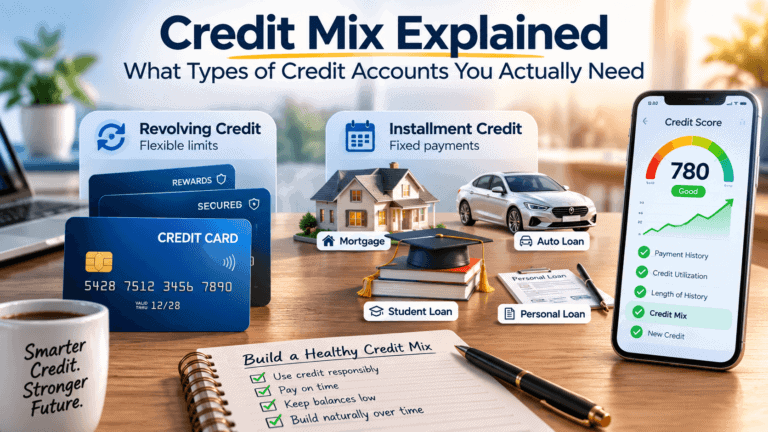
It can. Adding a different type of account, such as an installment loan after starting with a revolving credit card, may offer some credit mix benefit, though this is a smaller factor compared to payment history and utilization.
Should I wait even longer if I’m planning to apply for a mortgage soon?
Generally, yes. It’s common practice to avoid opening new credit accounts in the months leading up to a mortgage application, since new inquiries and accounts can affect underwriting.
What if I was pre-approved for a card — does that change the timing advice?
A pre-approval can reduce (though not always eliminate) the risk of a hard inquiry resulting in a denial, but the broader timing considerations around account age and payment history still apply.
Conclusion
Building credit from zero is a patience game as much as a strategy game. While there’s no universal rule for exactly how long to wait before applying for a second account, giving a first account enough time to generate a score and demonstrate a consistent payment history generally leads to stronger approval odds and better terms down the line. Rushing the process rarely speeds up real progress — it just adds unnecessary risk to a file that’s still finding its footing.
Your Action Plan for TODAY
- Check how old your first credit account is and whether a score has been generated yet.
- Review your payment history on that account for consistency.
- If you’re considering a second account, identify a genuine reason for it rather than impatience alone.
- Avoid applying for multiple new accounts within a short window.
- If a major application like a mortgage is on the horizon, hold off on new credit until after it’s complete.
Related Guides
- How to Build Credit from Zero: A Complete Guide for No Credit History in 2026
- Hard Inquiry vs Soft Inquiry: Credit Score 2026
- Credit Mix Explained: What Types of Credit Accounts You Actually Need
Disclaimer
This article is for educational and informational purposes only and does not constitute personalized financial advice. Credit scoring models and lender approval criteria may change over time. Individual results depend on personal financial circumstances and credit behavior. Readers should consult a qualified financial professional before applying for new credit.
Sources & References
- FICO — myfico.com
- Consumer Financial Protection Bureau (CFPB) — consumerfinance.gov
- Experian, Equifax, and TransUnion consumer education resources